Table of Contents
- Tax Credit vs Rebate vs Tax Deduction: What Actually Applies to Home Batteries
- Home Battery Rebate Eligibility: Who Qualifies and What You Need
- Federal Battery Rebate Rules: The Cheaper Home Batteries Program Explained
- Home Battery Tax Deduction: When You Can Claim It
- Business Solar Battery Tax Deduction: Rules for Small Business Owners
- Battery Capacity Limits, Approved Systems and Eligible Installers
- How to Apply: Step-by-Step Documentation Checklist
- Worked Examples: What You Could Save
- Frequently Asked Questions
Last Updated: October 16, 2026
Tax Credit vs Rebate vs Tax Deduction: What Actually Applies to Home Batteries
There is no federal tax credit for home batteries in Australia. None. If you’ve read otherwise, you’ve read American content repackaged for search engines. What we actually have is a rebate scheme, a business tax deduction, and state-level programs that all work differently. At GridFree Solar, we field questions about tax credit eligibility for home battery storage systems almost daily, and the confusion traces back to this one misunderstanding. This guide sorts out what each term means, who qualifies, and how to claim.
Why the Terminology Matters for Your Claim
A tax credit reduces the tax you owe, dollar for dollar. A rebate is a discount applied to your upfront cost. A tax deduction reduces your taxable income.
Get these mixed up and you’ll budget for the wrong number. A rebate cuts what you pay today. A deduction saves you a fraction of the cost at tax time, at your marginal rate.
The Australian Taxation Office guidance on deductions is clear on how deductions work. But it won’t help you claim a credit that doesn’t exist.
Home Battery Rebate Eligibility: Who Qualifies and What You Need
Home battery rebate eligibility comes down to three things: where you live, whether the property is your primary residence, and whether you have (or are installing) solar.
The federal scheme is administered through the Clean Energy Regulator’s Cheaper Home Batteries Program. State programs layer on top, each with their own rules.
Residency, Income and Primary Residence Rules
Most rebate programs require the battery to be installed at your primary residence; investment properties and holiday homes usually don’t qualify. Some state schemes apply income thresholds or property value caps, others don’t, so a jurisdiction-by-jurisdiction comparison matters.
- Primary residence: required for most rebates
- Income thresholds: apply to some state schemes only
- Existing solar: usually required, but check your state
- Approved installer: mandatory for every program
Federal Battery Rebate Rules: The Cheaper Home Batteries Program Explained
Federal battery rebate rules are set by the Cheaper Home Batteries Program, which provides an upfront discount on eligible battery installations. The discount is applied at the point of sale by your installer, not claimed later through your tax return, that’s the part most people miss. Eligibility is tied to approved battery models and accredited installers; if either falls outside the rules, the discount doesn’t apply.
Ask your installer for the rebate paperwork before you sign. If they can’t show you how the discount is calculated, find another installer.
Home Battery Tax Deduction: When You Can Claim It
A home battery tax deduction generally does not apply to a private residence. You can’t deduct a battery installed at your own home against personal income, the ATO treats private-use assets as non-deductible. It changes if the battery produces income or the property is a business premises.
Business Solar Battery Tax Deduction: Rules for Small Business Owners
Business solar battery tax deduction rules are where real money sits. If you run a small business and the battery supports income-producing activity, you may be able to claim it.
Two paths exist:
- Immediate deduction under temporary full expensing rules, if they apply to your business and the asset
- Depreciation over the effective life of the battery, claimed year by year
The ATO’s guide to business asset depreciation sets out how effective life is calculated. Talk to your accountant before assuming either path applies.
Claiming a private home battery as a business deduction is a common mistake. If the ATO audits and finds no income-producing use, you’ll repay the deduction plus penalties.
Battery Capacity Limits, Approved Systems and Eligible Installers
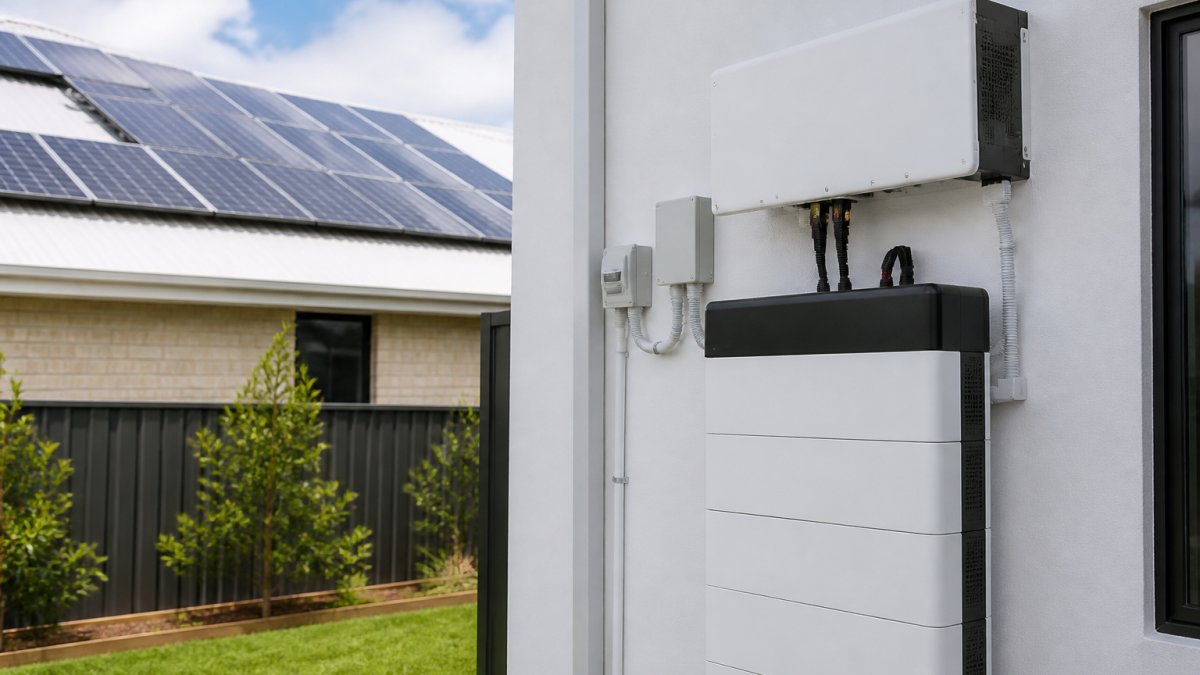
Battery capacity limits and approved system rules decide whether you qualify at all. The federal program caps eligibility by nominal capacity in kilowatt-hours, and the discount is calculated per kilowatt-hour of eligible capacity, so battery size directly determines benefit size. Three boxes must be ticked:
- Approved battery: listed on the Clean Energy Council’s approved products list
- Eligible system: meets capacity and installation requirements, including a compliant inverter and grid connection
- Approved installer: CEC accredited, with the accreditation number recorded on the paperwork
Nominal vs Usable Capacity: Why the Distinction Costs You Money
Every battery has two capacity figures, and confusing them is one of the most common reasons a quote looks better than the rebate it delivers.
- Nominal capacity is the total rated storage in kilowatt-hours (kWh), and is the figure the federal program uses to assess eligibility.
- Usable capacity is the portion you can actually draw on after the depth-of-discharge limit, most lithium batteries allow 80% to 95% of nominal capacity.
A battery marketed as 10 kWh nominal may only deliver around 8 to 9.5 kWh usable. The rebate is calculated on eligible nominal capacity, but bill savings depend on usable capacity. If a salesperson quotes savings based on nominal figures, ask for the usable number too.
How the Federal Discount Is Calculated
The Cheaper Home Batteries Program applies a per-kilowatt-hour discount to eligible installed capacity, subject to a program cap. It is not a flat amount or a percentage of your invoice, it scales with battery size, up to the cap. Two consequences follow:
- A larger battery earns a larger discount, up to the cap. Beyond the cap, additional capacity is not subsidised.
- The discount is applied at the point of sale, not refunded later, and shown as a line item on the quote.
Because the rate and cap can be adjusted, always ask your installer for the current figures in writing, don’t rely on a figure you read six months ago.
Approved Products and Accredited Installers
The Clean Energy Council maintains the approved products list. If your chosen battery is not on it, no federal discount applies, regardless of how efficient or well-reviewed the model is. Check the list yourself rather than taking a retailer’s word for it. Accreditation works the same way: only a CEC-accredited installer can lodge the claim, so if the person quoting you is not accredited or is subcontracting, confirm in writing who will sign off and lodge the paperwork.
| Requirement | What It Means | Why It Matters |
|---|---|---|
| Approved battery | Listed on the CEC approved products list | No listing, no rebate |
| Capacity limit | Nominal capacity within the program cap | Capacity above the cap is not subsidised |
| Accredited installer | CEC-accredited tradesperson | Unaccredited work voids the claim |
| Primary residence | Owner-occupied home | Investment properties excluded |
| Existing solar | Panels already installed or planned | Most programs require it |
| Grid connection | Compliant inverter and connection | Off-grid systems generally fall outside the scheme |
Ask for the nominal capacity, the usable capacity, and the per-kilowatt-hour discount rate in the same document. If any one of the three is missing, the quote is incomplete.
Edge Cases Worth Checking Before You Sign
Not every household fits the standard pattern, and the rules treat some situations differently:
- Battery-only installations: most programs expect solar to be installed or planned; a battery with no solar behind it usually won’t qualify.
- Off-grid homes: systems not connected to the grid generally fall outside the federal scheme, which is designed around grid interaction.
- New builds: eligibility depends on when the solar and battery are commissioned and whether the property is your primary residence at that point.
- Renters and landlords: the rebate attaches to the property and installation, not the occupant, a landlord can typically claim where the property qualifies, but a renter usually cannot claim in their own name.
- Existing solar households: adding a battery to an existing system is a common and generally eligible path, provided the battery and installer meet the rules.
If your situation sits in any of these categories, get eligibility confirmed in writing before paying a deposit.
How to Apply: Step-by-Step Documentation Checklist
Applying for a battery rebate is mostly a paperwork exercise. Get the documents right and the process is straightforward. Get them wrong and you’ll wait weeks for a fix.
Total time: 1-2 hours of your own admin, plus your installer’s lodgement.
What you’ll need:
- Proof of property ownership or rates notice
- Recent electricity bill
- Solar system details, if already installed
- Photo ID matching the property owner
The steps:
- Check eligibility against your state and federal programs before you sign anything.
- Confirm your installer is CEC accredited and ask for their accreditation number.
- Verify the battery model appears on the approved products list.
- Sign the installation contract with the rebate discount itemised.
- Let your installer lodge the rebate claim through the relevant program portal.
- Keep every document, including the Certificate of Electrical Safety and compliance certificates.
- Retain records for tax time if any portion is business-related.
The rebate is applied upfront by your installer, not refunded later. If a quote doesn’t show the discount as a line item, ask why.
Worked Examples: What You Could Save
Exact savings depend on your battery size, your state or territory, and your electricity use. What follows is a framework for estimating your own figures, plus worked examples showing how capacity caps and program limits change the outcome. Treat every figure as illustrative, not a quote.
The Four Components of Your Return
- Upfront discount: reduces your installation cost on day one, calculated per kilowatt-hour of eligible nominal capacity, up to the program cap.
- Bill savings: depend on how much solar you store and use rather than export, a battery shifts evening consumption onto stored solar, displacing grid purchases at your retail rate.
- Export earnings: some retailers pay a feed-in tariff for power sent back to the grid, including during peak evening windows.
- Business deduction: only if the battery supports income-producing activity, and only at your marginal rate.
These stack: a rebate reduces what you pay, a feed-in tariff improves what you earn, and a business deduction reduces your taxable income. They are not alternatives.
Worked Example 1: A Mid-Size Battery at the Cap
Consider a household installing a battery with a nominal capacity at or below the program cap, alongside an existing solar system.
- Installed cost before discount: the quoted price from your installer
- Federal discount: the per-kilowatt-hour rate multiplied by eligible nominal capacity
- Out-of-pocket cost: installed cost minus the discount
- Annual bill saving: driven by usable capacity and evening consumption, not nominal capacity
The discount is capped, so once your battery reaches the cap, a larger model increases your cost without increasing your subsidy. The extra capacity may still pay for itself through bill savings, but on its own merits, not the rebate.
Worked Example 2: A Smaller Battery Below the Cap
A smaller battery below the cap earns a proportionally smaller discount, but the discount applies to every eligible kilowatt-hour. The trade-off:
- Lower upfront cost and lower discount
- Lower usable storage, so fewer evening hours covered by stored solar
- Faster payback if your evening consumption is modest
For a household that uses most of its power during the day, a smaller battery can deliver a better return than a larger one, because there is less evening load to serve.
Worked Example 3: Business Use
Where the battery supports income-producing activity, the calculation changes again. The upfront discount still applies at the point of sale. Separately, the business portion of the asset may be deductible, either immediately under temporary full expensing rules, if they apply to your business and the asset, or through depreciation over the battery’s effective life.
The ATO’s guide to business asset depreciation sets out how effective life is calculated. The deduction saves you a fraction of the cost at your marginal rate, not the full amount. A 30% marginal rate on a deductible portion is a very different number from a dollar-for-dollar rebate, and conflating the two is the single most common budgeting error we see.
Stacking Rules: What Can and Cannot Be Combined
- Federal discount plus state or territory rebate: generally stackable where both programs apply, but each has its own eligibility rules and caps.
- Rebate plus feed-in tariff: stackable. The rebate reduces your purchase cost; the tariff improves your export earnings.
- Rebate plus business deduction: the deduction applies to your net cost after the rebate, not the pre-rebate price. Claiming a deduction on the full invoice is a common mistake.
- Multiple state rebates: usually not stackable within the same jurisdiction. Check the program rules.
A rebate is not a tax credit. It reduces your purchase price, not your tax bill. If you are relying on a tax refund to fund the purchase, you are budgeting against the wrong mechanism. Speak to a registered tax agent before assuming any incentive reduces tax owed.
How to Run Your Own Numbers
- Get the installed cost, discount amount, and usable capacity in writing from your installer.
- Estimate your evening consumption in kilowatt-hours from a recent bill.
- Multiply evening consumption by your retail rate to estimate maximum annual bill saving.
- Subtract the discount from the installed cost to get your out-of-pocket figure.
- Divide out-of-pocket cost by annual saving for a rough payback period.
A worked example using your own bill beats any generic calculator, so ask your installer to run it with you before you sign.
Frequently Asked Questions
Can I claim a home battery on tax in Australia?
For most homeowners, a home battery is not tax deductible because it is a private household asset. However, if the battery is installed at a property used to earn income, such as a rental or home-based business, you may be able to claim depreciation over its effective life. Small business owners may also qualify for an instant asset write-off if the battery meets the relevant turnover and cost thresholds. Check the current rules with the ATO or a registered tax agent before lodging your claim.
Are home battery systems eligible for a tax credit in Australia?
Australia does not offer a tax credit for home batteries in the way some other countries do. Instead, eligible households receive an upfront discount through the Cheaper Home Batteries Program, which is applied at the point of sale by an approved installer. This reduces the purchase price rather than your taxable income. The distinction matters because a rebate is a discount on the system cost, while a tax deduction reduces your assessable income.
Can I claim both a battery rebate and a tax deduction?
You can receive the federal rebate and, in limited circumstances, also claim a tax deduction if the battery is used for an income-producing purpose. However, you cannot double-dip on the same expense. If you claim a deduction, you must reduce the deductible amount by any rebate received. For a typical owner-occupied home, the rebate is the only benefit available. Speak to a tax agent about your specific situation.
Do I need solar panels to qualify for a home battery rebate?
Yes. To access the federal rebate, the battery must be connected to a new or existing solar panel system at the same property. Standalone batteries without solar are not eligible under the current program rules. The battery also needs to be a approved model with a nominal capacity of at least 5 kilowatt-hours, installed by a Clean Energy Council accredited installer who will handle the rebate paperwork on your behalf.